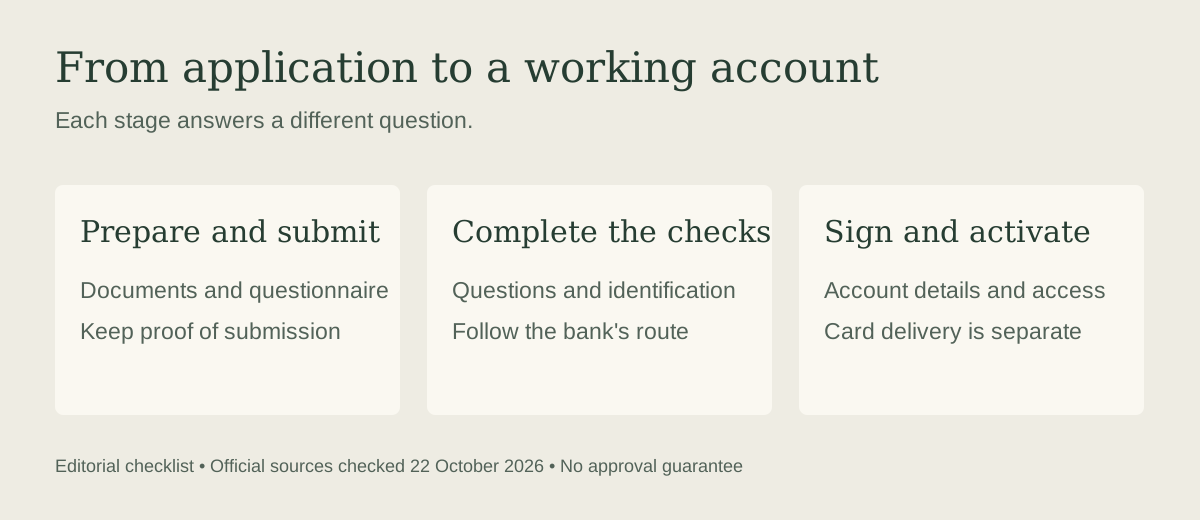
To open a bank account in Armenia as a foreigner, prepare your documents, submit the bank's application and complete its identity and background checks. Then finish the agreement and any activation steps. A confirmation that your files arrived is not the same thing as a working account.
This guide is for an adult applying for a personal account. If you have not chosen a bank yet, use our bank comparison first. Here we focus on getting the application right and knowing what to do at each stage.
TL;DR
- Gather identification, address evidence and documents explaining your money. The exact file depends on your bank, status and circumstances, as the National Services Gateway explains.
- Use the bank's own questionnaire. Save the completed version, attachments and submission confirmation.
- A social number, notarised translation and branch visit are not identical requirements for every foreign applicant. The specific examples below show the differences.
- Describe your real income, savings and expected transfers. Do not copy an example that does not match your documents.
- After approval, finish identification, signing and any funding requirement. Confirm account access separately from receiving a card.
Official sources checked on 22 October 2026. These instructions explain published procedures, not a guarantee that a bank will approve your application. No test application or individual professional review is claimed.
What should you do before submitting anything?
Find the official instructions for an individual foreign customer and establish which route you are using: a branch application, online preliminary review or a specific remote-onboarding programme. Keep the document list and application form together.
The government guide says requirements can vary by country of origin and the bank's assessment. A page for Armenian citizens, a business account or an existing app user may describe a different process from yours.
Your overall sequence is:
- Assemble the documents that identify you and explain the account.
- Resolve language, translation and social-number requirements for that route.
- Complete the questionnaire and submit it through the stated channel.
- Answer further questions and complete identification.
- Sign the relevant documents and receive the account details.
- Complete activation and check access from your own device.
That order helps you avoid arranging an incoming transfer while the bank is still reviewing your file.
Step 1. Which documents should you prepare?
Start with your identity, address and financial evidence, then add the bank's own forms. Keep the originals available where the procedure requires them; a scan sent for review does not automatically replace the final document check.
Ameriabank's document list effective 23 June 2026 separates non-citizen identification and address evidence from additional information. Its additional section includes other-bank statements covering at least one year, employment evidence and property or business documents. Footnote 6 says those additional items are not mandatory unless the bank specifically requests them, although they matter to due diligence.
ACBA's non-resident application lists identification, residence-address evidence, the previous year's income-tax statement, documents showing lawful funds, an employer contract and an account statement for the last six months. It allows further requests. These are examples of different published lists, not a combined compulsory pack for every bank.
Table caption: What each part of your application should establish| Part of the file | Examples from the official lists | What to keep consistent |
|---|---|---|
| Identity | Valid identification and the bank's customer details | Name, document number and expiry date |
| Address | An address-bearing identity document, an authority-issued reference, utility receipt or another document accepted for the route | The address you declare and the address the evidence actually supports |
| Income and source of funds | Employment evidence, bank statements, a tax statement or documents supporting an asset sale | Who paid you, why and how the money reached your account |
| Eligibility for the chosen route | A residence permit, property evidence or another qualifying basis where specifically required | Do not substitute a lease for a requirement that says ownership |
| Bank forms | Application-agreement, questionnaire, tax self-certification and signature documents where applicable | Complete answers that agree with the supporting file |
The IDBank foreign-passport leaflet linked from its English account page, for example, specifies a residence permit or residential-property ownership in the applicant's name with a residence certificate at that property. That is a reason to establish eligibility before preparing the rest of this particular application. It is not a rule we can apply to every Armenian bank.
If you are using a tenancy document as address evidence under a route that accepts it, keep the signed version showing the actual parties and address. Our rental-agreement guide deals with that document; this page does not repeat how to negotiate the tenancy.
Step 2. Do you need translations or a social number?
Use the requirement for the bank and service you are applying to. Neither “everyone needs the same notarised translation” nor “foreigners never need a social number” is a safe reading of the official material.
What language does the bank accept?
Under section 1.5 of Ameriabank's June 2026 document list, documents in foreign languages other than Russian or English generally need a notarised translation. The same section exempts address-confirming documents from that translation requirement, except those issued by a competent foreign-state authority. Keep that exception attached to the rule.
For example, an employment document written only in French and an English document are not in the same position under that published rule. The language you speak is also a different question from the language of the documents you submit.
ACBA makes another distinction: its English application page explicitly says “Please complete the application in Armenian.” Arrange help understanding and completing the form if needed, then read the finished answers before signing. An English interface does not itself mean an English questionnaire is accepted.
What if you do not have an Armenian social number?
Check whether the selected route asks for the number, evidence of it or a statement of its absence. Evocabank's ordinary account-opening instructions list a passport and social card or a statement on its absence, or an identification card, with additional documents possible.
The government guide describes social-number requests as bank-dependent. The absence of that item from a different programme's short checklist does not prove it can never be requested.
If a form asks for a number you do not have, do not invent one or insert a foreign tax number in its place. Establish the applicable alternative. Follow the separate Public Services Number guide for the documents and appointment needed to obtain the Armenian number.
Step 3. How should you explain the account and your money?
Describe the real use of the account and connect it to evidence. “Personal expenses after relocation” can explain the purpose; it does not explain where a large opening transfer came from.
Ameriabank's remote application asks separately about income, the source of funds and expected monthly credits. Think about those as separate answers:
- Income: what you earn and from whom.
- Source of the money you will transfer: how you accumulated the particular funds.
- Expected account activity: what will actually arrive and leave after opening.
Consider this hypothetical example, with invented figures used only to show the distinction. You earn EUR 2,500 monthly and expect to move EUR 5,000 of existing savings into the new account. If both arrive in the first month, planned credits are EUR 7,500, then EUR 2,500 in later months if the salary continues to arrive there. That is our arithmetic, not a bank threshold or an approved application answer.
The evidence should explain both flows: employment and salary records for the regular payment, and statements or other records supporting how the savings accumulated. If a payment is instead the proceeds of a property sale, describe the sale and provide the relevant money trail. Moving it from your own overseas account explains the transfer route, but not necessarily its original source.
Do not describe client payments as savings to make the file appear simpler. If the intended activity is business activity, establish the appropriate account type with the bank; this is not an entrepreneur or company-account instruction.
What should you put in tax-residency fields?
Answer the question actually asked. Citizenship, a residence permit and country of tax residence are separate fields in the Ameriabank application, which also provides for tax identification numbers.
Its document rules require applicable FATCA forms where the customer falls within the relevant US-person criteria. Do not choose a form solely from a sample filled in by someone with a different status. If your tax position is uncertain, resolve that factual question before signing the declaration; opening the account does not settle it.
Step 4. Where do you submit the application?
Use the channel stated for your chosen route, then keep proof of submission. Do not combine an older leaflet's email route with a newer card-order process and present the mixture as one official instruction.
How does ACBA's online application work?
The non-resident form asks you to download and complete its questionnaire, attach the completed file, upload the supporting documents and select a branch. The questionnaire upload states a 14 MB maximum. The supporting-document area uses different labels, so do not assume the same limit applies to every attachment.
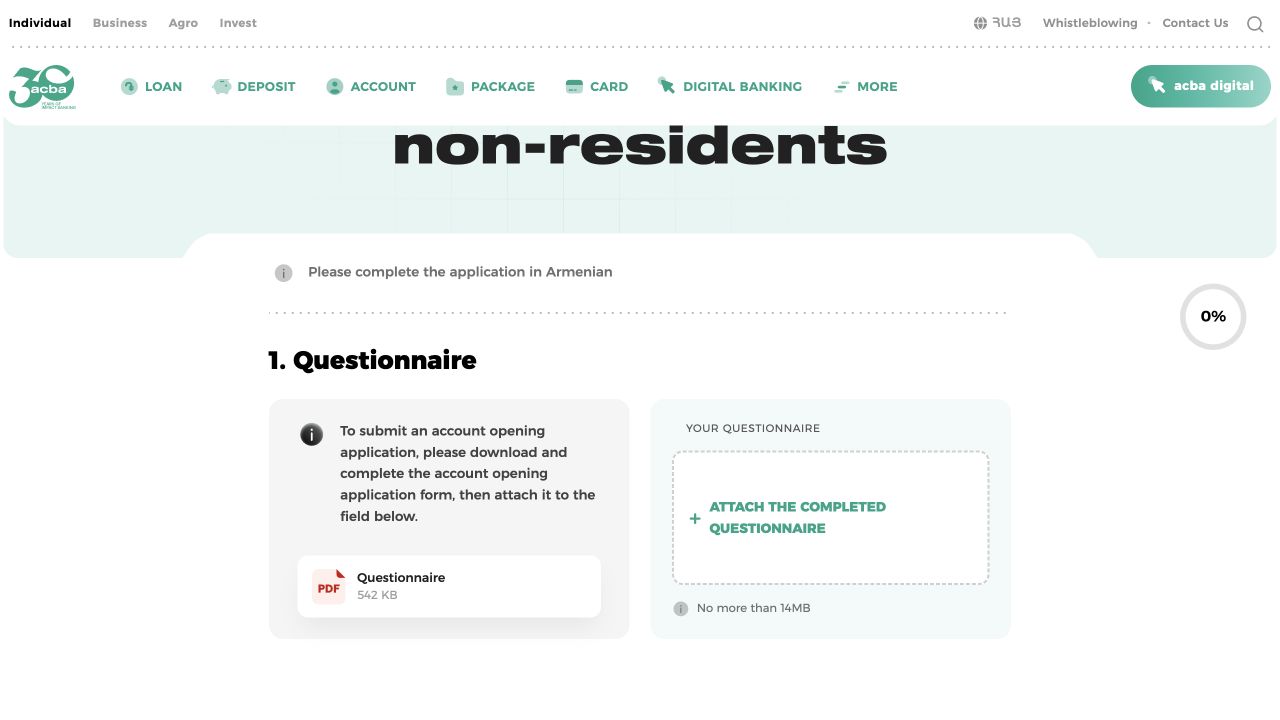
ACBA's official application page, saved 22 October 2026. The form is empty; no personal information was entered or submitted. Open the image to read the instructions.
Before submitting, check that every file opens, all required pages are present and the completed questionnaire is actually attached. Save your copy of the file set. ACBA says it will communicate its decision through the email or phone number in the questionnaire; keep both available.
What does IDBank publish for foreign customers?
The English leaflet currently linked from the bank's account page describes completing the KYC questionnaire, saving it as a PDF and sending the document set to nonresident@idbank.am, with an account-opening subject identifying the applicant. It then describes booking a branch visit through EarlyOne after confirmation that opening is possible.
There is an age warning: this English leaflet still names income certificates for 2021-2022. The Russian leaflet refers to 2024-2025 and describes uploading the file set through a card request. We therefore treat the English instructions as a published route with outdated details, not a newly issued procedure for every applicant. Get the current submission route confirmed before sending identity documents. Do not obtain obsolete tax-year certificates simply because they appear in that example.
Both leaflets describe a 72-hour review. That is not a promise that identification, a branch visit, card production and account activation will all finish in that time. Nor does it establish one response time for other banks.
How does Ameriabank's remote submission work?
Its non-citizen remote-opening page describes downloading, completing and signing the application-agreement, then sending it with identification and the other required documents to contact@ameriabank.am. It requires an existing account at another bank and includes country and risk restrictions.
Read the linked country-restriction list before relying on this route. The application says it is unavailable to individuals related to the listed countries. The exact relationship and risk assessment belong to the bank; do not reduce that wording to citizenship alone or interpret it as a ban on all Armenian banking.
After the complete file arrives, the bank describes arranging a video call. That is an identity-verification stage, not an account you can use merely because you sent an email.
Step 5. What happens during verification?
The bank checks the file and may ask further questions or documents before completing the service. Answer the particular request and keep your replies consistent with the original application.
Section 1.8 of Ameriabank's document list distinguishes starting review from copies from providing the service after the required originals, notarised copies or other accepted identification. A request for a scan and a completed identity check are different stages.
Evocabank's ordinary procedure says it will conclude the agreement and open the account within one business day after checking the authenticity and validity of the documents. That wording does not set a one-day total from first contact, and the same page allows additional review.
If the bank asks about a transfer, connect the amount, sender and underlying reason. If an attachment was unreadable, replace the file. If it asks for a current address document, sending the same expired document again does not resolve the request. Keep the application reference and a short list of what you sent and when.
Step 6. When is the account actually ready to use?
Treat approval as a milestone, then complete the remaining agreement and activation requirements. Receive the account details from the bank and establish whether you can receive and send the intended payments.
Ameriabank's remote procedure says that, after approval, you transfer at least USD 50 from the account at another bank to the new account. It describes activation once the transfer has arrived, electronic confirmation of the credit, and final account documents to sign and return. That funding step is not a complete quote for the bank's fees.
Evocabank's dedicated remote programme also describes a video call, a positive decision and an initial transfer of at least USD 50. It says the account becomes active after that payment is received and accessible. The programme has specific eligibility, so this is not a universal activation instruction for every Evocabank customer or every Armenian bank.
Before leaving a branch or finishing the remote process, use this practical checklist:
- Keep your copy of the signed agreement and applicable service terms.
- Check your name against the account details and identify the currency of each account.
- Obtain the correct instructions for the intended incoming transfer directly from the bank.
- Establish whether anything remains to be signed, verified or funded.
- Log into the banking service on your own device and verify access to your contact number.
- If you ordered a card, establish its delivery and activation separately.
Keep login details and one-time codes under your own control. If someone helps with translation or the paperwork, that help does not require them to manage your banking credentials.
What should you do if the process stops?
Identify the unfinished stage before sending another application. A missing attachment, a pending review and a refusal need different responses.
Table caption: Common account-opening problems and the next useful action| What happened | What to do next | What it does not establish |
|---|---|---|
| You received no submission confirmation | Check whether the official form or email accepted the file set, using the same application reference where available | That the account has been refused |
| The bank requested another document | Match the request to the missing fact, send the relevant evidence and retain your reply | That repeating the original attachment will resolve it |
| The bank approved the application but access is unavailable | Follow the remaining signing, identification or activation steps for that route | That a card or working account is already available |
| A stated review period has passed | Ask for the application's status and whether the file is complete | A guaranteed completion deadline for every later stage |
| The application was refused | Ask whether a missing document can be remedied or whether the route does not fit your circumstances | That the bank must disclose its entire assessment or another bank will approve you |
Do not change truthful details to get around a refusal. If you approach another bank, use that bank's actual requirements rather than assuming the first file can be submitted unchanged.
Questions about opening an account
Can I start before arriving in Armenia?
Yes, published routes include preliminary document review and specific remote programmes. A remote first contact does not mean every later stage is remote. Ameriabank and Evocabank describe conditional remote procedures above, while IDBank's linked English leaflet includes a branch visit.
Is a passport enough?
Do not plan on a passport-only application. The official examples request address, financial or other supporting evidence, depending on the route. The bank may ask for more after reviewing your file.
Can I use a rental agreement instead of a residence permit?
They establish different things. A tenancy document may support an address where accepted, but it is not a substitute for a route that expressly asks for a residence permit or property ownership. Read the eligibility and address requirements separately.
Do I need to translate every document into Armenian?
There is no identical rule across the sources reviewed. Ameriabank's stated language rule and address-document exception differ from ACBA's instruction to complete its application in Armenian. Apply the requirement to the particular document and form, rather than paying to translate everything by default.
Can someone complete identification for me?
Do not assume a representative can replace your own identity verification. The remote examples include a video call, and the bank's instructions determine what you must do personally. Help preparing or translating documents is different from being authorised to operate the account.
Should I transfer my savings as soon as approval arrives?
First complete the applicable account and activation instructions and obtain the correct payment details. An initial funding requirement is part of a specific procedure, not proof that every later transfer will be accepted without review. Keep the evidence for the intended savings transfer ready.
What should you have at the end?
You should know which accounts were opened, have the relevant signed documents, understand any remaining restrictions and be able to access the service yourself. A submitted questionnaire or promised card is only part of that result.
The main sources are the National Services Gateway, the linked bank forms and the bank-specific procedures above. They were checked on the stated date; IDBank's dated English leaflet is explicitly qualified. For the separate question of product costs and suitability, return to choosing a bank in Armenia. This page deals with completing the application, without repeating the tariff comparison.