The best bank in Armenia for a non-resident depends on what you need it to do. A cheap account is little help if you cannot meet the bank's document requirements. A card with free maintenance can still become expensive if you withdraw rent in cash every month.
Start with your situation: are you moving to Armenia, keeping an account from abroad, receiving a local salary or transferring savings? Those are different jobs. This guide compares selected personal products at Evocabank, ACBA, IDBank, Ameriabank and Ardshinbank, using their published conditions rather than an overall star rating.
TL;DR
- Choose a bank whose published foreign-client requirements match the documents you have. A residence permit, citizenship and the tariff's resident category are different questions.
- For a basic account without a card, compare the opening charge and ongoing maintenance together. The account-only examples below deliberately exclude transactions.
- Read the non-resident row and its footnotes. The free opening offer at the top of a page may have a separate foreign-client charge underneath.
- Compare your repeated operations before choosing a card: cash withdrawals and international transfers can cost more than maintenance.
- Remote application, managing an existing account online and fully remote first-time onboarding are different services. Evocabank's dedicated remote programme has its own eligibility and price.
Terms checked on 22 October 2026. This is an editorial comparison of published personal banking conditions, not an assessment of bank solvency, a promise of approval or advice about investments. We have not submitted test applications or independently tested English-language support. For documents, submission and activation, follow the separate account-opening guide.
Which banks should go on your shortlist?
For a simple current account, start by comparing Evocabank, ACBA and IDBank under the same account-only scenario. Consider Ameriabank as a specific combination of account, card and digital services. Ardshinbank's named digital card is useful for a card comparison, but its issue price is not the price of every account service.
Table caption: Selected personal products: published charges checked on 22 October 2026| Bank and product | Starting charge | Ongoing charge | What changes the decision? |
|---|---|---|---|
| Evocabank ordinary current account | 10,000 AMD for a non-resident foreigner | Individual account maintenance: free | The separate remote programme has different charges. A card and transactions are outside this row. |
| ACBA current account | 15,000 AMD when a non-resident opens their first account | 300 AMD monthly unless an exemption applies | A 50,000 AMD average daily balance is one non-resident exemption; other qualifying conditions exist. |
| IDBank current account | 10,000 AMD for the first non-resident account under the cited tariff row | 1,000 AMD monthly or 12,000 AMD annually | Foreign-passport eligibility matters. The tariff separately lists 25,000 AMD for remote identification. |
| Ameriabank Standard | 20,000 AMD non-citizen due-diligence charge if the bank approves the relationship | Depends on the selected services and applicable conditions | The due-diligence fee, account-opening fee, card and digital services are separate lines, with specific exemptions. |
| Ardshinbank Visa Gold Debit Digital Non Resident | 25,000 AMD for issue of this card | Maintenance of this card: free | A card comparison, not a complete onboarding quote. Own-bank ATM withdrawals cost 0.5%. |
This is a selected comparison, not a survey of every Armenian bank. We left Inecobank out of the fresh numerical table because its tariff documents could not be retrieved during this update. We have not attached today's checking date to an older saved tariff.
The table answers “what is this charge for?” before “which is cheapest?” It would be misleading to compare a whole remote-service programme with the annual fee for a single digital card.
Can you choose a bank without an Armenian residence permit?
Yes, non-resident banking exists, but there is no universal passport-only route. The National Services Gateway describes identity checks, purpose or economic ties, income, address evidence and possible additional documents. It also warns that requirements can depend on country of origin.
That makes the document filter worth applying before you compare card colours or benefits. Two banks can advertise non-resident accounts while asking for quite different evidence.
What makes IDBank a different shortlist decision?
The bank's published foreign-passport leaflet specifies a residence permit or residential property ownership in the applicant's name together with a certificate of residence at that property. It also lists income evidence and a main-bank statement showing regular receipts over the previous six months.
An ordinary tenancy agreement is not listed as a replacement for the permit or ownership requirement in that section. If you have just arrived and rent your home, the low opening charge alone is not a sufficient reason to make IDBank your only plan.
This is a Russian-language bank leaflet and some examples reflect that audience. We use it for the requirement it actually states, not to claim every nationality must produce a Russian tax document. The downloaded version refers to income documents for 2024-2025. It is more recent in that respect than the older English leaflet cited in some search results.
How do ACBA and Ameriabank describe their checks?
ACBA's non-resident application lists identification, residence-address evidence, the previous year's income-tax statement, lawful source-of-funds documents, an employer contract and a bank statement for the last six months. Further documents may be requested. The list helps you judge whether your file fits the process; uploading it is not automatic approval.
Ameriabank's published document list asks non-citizens for identification and address evidence. Its additional-information section includes other-bank statements covering at least one year, employment evidence and property or business documents. The document is effective from 23 June 2026, and footnote 6 says the additional items are not mandatory unless the bank requests them, although they matter to due diligence.
That qualification matters. A possible additional request should not become a blanket rule that every foreign applicant needs the same employment history. Nor does a shorter published list guarantee easier approval.
What does a basic account cost over a year?
Under the narrow scenario below, ordinary Evocabank has the lowest quoted account charges among these three products. That conclusion covers account opening and maintenance only. It does not establish the cheapest bank for someone who needs a card, frequent cash or international transfers.
Our example assumes a personal AMD current account held for twelve months, using the cited non-resident tariff rows, with no card, transactions, paid extras or individual opening-fee exemption. These are our calculations from the Evocabank, ACBA and IDBank schedules.
Table caption: Illustrative first-year account charges, excluding cards and operations| Product and condition | Calculation | Account charges |
|---|---|---|
| Evocabank ordinary current account | 10,000 + 0 | 10,000 AMD |
| ACBA, monthly fee applies throughout | 15,000 + 300 × 12 | 18,600 AMD |
| ACBA, maintenance exemption met throughout | 15,000 + 0 | 15,000 AMD |
| IDBank, cited first-account row, without remote identification | 10,000 + 1,000 × 12 | 22,000 AMD |
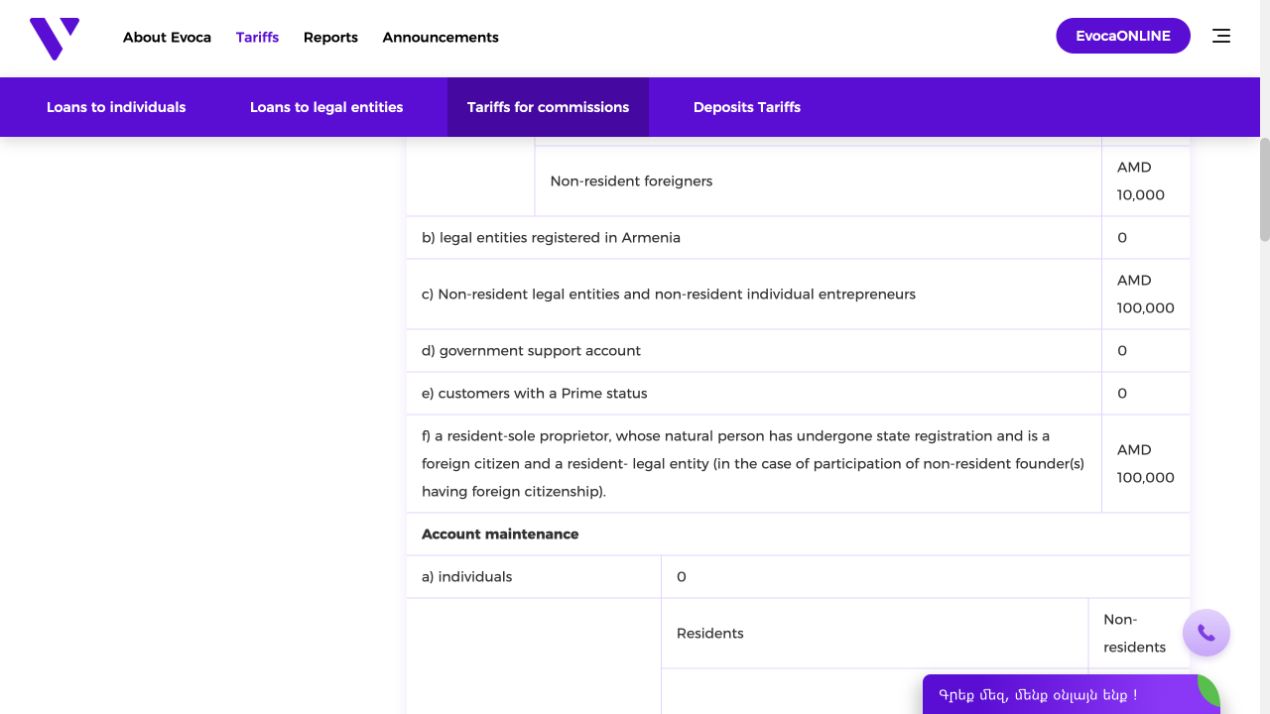
Official Evocabank current-account page, screenshot saved 22 October 2026. Open the image to read the original rows. The page was marked updated 19 October 2026.
ACBA's 50,000 AMD average daily balance is money in your account, not another fee to add to the total. The service conditions explain the threshold and other exemptions, including how a qualifying current or deposit account can cover the balance requirement.
Here is a simplified illustration of the word “average”: if your balance is 50,000 AMD for half of a 30-day month and zero for the other half, the arithmetic average is 25,000 AMD, not 50,000. This is our example, not a statement about the bank's detailed booking rules. A large top-up at the end does not necessarily achieve the required average.
You also need to keep an account operational. ACBA's conditions describe restrictions when unpaid fees accumulate; IDBank lists a separate inactive-account charge. Neither belongs in a cheerful “free forever” claim. Our table assumes an actively maintained account with fees paid.
Why does Ameriabank need a separate calculation?
Its published tariff connects several services and exemptions, so adding every visible charge can overstate the bill, while quoting free Smart can understate it. Use the exact package and eligibility conditions.
In the tariff effective from 11 September 2026, the regular Smart opening package is explicitly limited to Armenian citizens. Moving to Armenia does not make that particular citizenship condition disappear.
Standard's 20,000 AMD non-citizen due-diligence charge is payable when the bank approves establishing the relationship, with stated exceptions. It should not be described as an inevitable non-refundable fee just for an unsuccessful application. Account opening is another line; ordering certain products, including a payment card, can waive the relevant account-opening charge.
There is also a dated concession: the listed 1,000 AMD per calendar half-year low-activity account-management charge is not applicable through 30 June 2027 inclusive. Do not add it to today's bill as if there were no footnote. Equally, do not extend that concession indefinitely when planning a longer relationship. These details are in the same tariff.
The useful comparison is the actual card, account and digital service you intend to use, after exemptions. We have not invented an all-in Ameriabank annual total without that product choice.
How much can cash withdrawals add to a free-maintenance card?
Enough to change the choice if you regularly pay rent or other large expenses in cash. Look at the ATM fee for your particular card and the network you will actually use.
The Ardshinbank Visa Gold Debit Digital Non Resident tariff, effective 25 March 2026, lists 25,000 AMD for issue, free card maintenance and 0.5% at the bank's own ATMs. The product is offered in AMD, USD and EUR.
Suppose you withdraw 300,000 AMD each month from an AMD account through that own-bank ATM route. Our calculation is 300,000 × 0.5% = 1,500 AMD per withdrawal, or 18,000 AMD over twelve such withdrawals. Adding the listed issue price gives 43,000 AMD for those two components in the first year. This excludes other banking fees and any currency conversion.
If you mostly pay by card, that cash example will overstate your needs. If your landlord wants cash, it becomes more relevant. The rental-agreement guide covers agreeing the payment method and recording each payment; it does not determine the bank's fee.
The product page starts its order instructions with logging into the bank's app. That is evidence of how to order this card within that service, not proof that every new foreign customer can complete initial onboarding remotely.
What changes if you send money abroad regularly?
Compare the non-resident transfer line, its minimum charge and the payment route. A small percentage in a general row is not always the tariff for your customer category.
IDBank's tariff lists 1%, minimum 30,000 AMD, for non-resident individuals' USD/EUR transfers under the cited OUR option, including online. The same page has different general rows, so quoting only a lower headline percentage would miss the relevant distinction.
For a hypothetical eligible transfer with a fee-calculation base equivalent to 1,000,000 AMD, one percent is 10,000 AMD. The 30,000 AMD minimum would therefore control under that row. This is an illustration of the minimum, not a live exchange-rate quote or a complete transfer bill. Correspondent charges, conversion, the receiving bank and whether the route is available still matter.
Your practical comparison should name the sending country, currency and receiving account. Receiving savings from your own overseas account is also a different question from sending regular business receipts through a personal account. We do not assume a particular country of citizenship or an income stream from Russia.
A published currency account and a SWIFT code do not establish that every proposed transfer will be accepted. They are only part of the comparison.
Is a remote account worth paying for before you move?
It may be, if you need banking before arrival and qualify for the specific programme. It is much harder to justify its price if an ordinary account after arrival meets your needs.
Evocabank's dedicated remote service for non-residents lists 50,000 AMD opening and 250,000 AMD annual service for individuals. Those two charges total 300,000 AMD for the first year, our calculation before operations. The page separately lists 0.5% for non-cash credits and client transfers.
The programme describes property ownership, Armenian sole-proprietor registration, participation in an Armenian company and a deposit route among its qualifying categories. Its language versions describe the deposit amount and term inconsistently, so we do not present one disputed threshold as a settled offer.
This programme is not the same product as the ordinary current-account tariff, whose non-resident opening and individual maintenance charges appear in our first table. “Online banking is available” does not mean “the dedicated remote programme has ordinary account pricing.”
If you are arriving soon, that distinction may remove remote opening from your priorities altogether. Keep it on the shortlist only when it solves a real timing problem.
How should you make the final choice?
Shortlist banks that fit your documents, then compare the bundle you will use. The account-only table is a starting point for that decision, not a verdict on the whole bank.
For a newcomer who rents and has no residence permit, the IDBank leaflet's permit-or-property condition needs attention before its price. ACBA, Evocabank and Ameriabank offer other published material to assess against your circumstances, without any promise that one will approve your file.
For regular cash expenses, the ATM route deserves its own line in your budget. For international transfers, the applicable minimum can matter more than annual maintenance. For a salary account, compare your employer's specific offer rather than assuming the ordinary non-resident tariff is the payroll deal.
Put these charges alongside your other monthly expenses in the cost-of-living guide. If you need a branch near home, the Yerevan district comparison helps put convenience in context. We have not scored branch queues or staff fluency from online anecdotes.
Questions before you choose
Which bank is cheapest for a foreigner?
Among the three account-only scenarios calculated here, ordinary Evocabank has the lowest listed opening-plus-maintenance total. That excludes a card and transactions. A different cash or transfer pattern can change the result.
Does a residence permit automatically give me resident pricing?
Do not assume that every bank uses the same definition for every charge. Ameriabank's cited due-diligence fee is framed around non-citizenship, while other rows refer to non-residents. Establish the customer category for the particular product rather than treating immigration status as a universal tariff switch.
Which bank has the best English support?
We have not independently tested support and cannot award a defensible winner. The English-language forum discussion in the research contains conflicting individual experiences. An English product page helps you read the offer, but it does not prove the quality or language of every support interaction.
Is a free-maintenance card free banking?
No. Issue, identification, account services, cash and transfers may have separate fees. Some charges are waived when you take another product, so neither adding every line nor ignoring them gives a reliable total.
Can I choose a bank before travelling?
Yes, the published eligibility and product terms let you narrow the choices before arrival. Fully remote first-time onboarding has to be established for the actual programme and your circumstances. An online application or an existing-client card order is not enough to prove it.
Does meeting the published conditions guarantee approval?
No, the bank still assesses the individual application and can request further evidence. A tariff tells you how a service is priced, not that every applicant can obtain it. The comparison does not estimate your approval probability.
Sources and limits
The linked bank schedules and document lists support the individual claims above. The National Services Gateway provides the general context; it does not replace bank-specific requirements. Some official sources are in Russian. Ameriabank's document list was refreshed to the June 2026 edition during the account-opening research.
The comparison is based on published terms checked on the stated date, not successful account-opening stories, calls or a financial-strength analysis. We have not measured approval probabilities or verified a named expert review. Choose the product whose eligibility, full set of charges and intended operations match your move.